Truck Loans Australia :: Articles

Simple Tips On Getting Your Loan

What are some simple tips for getting a loan?

Simple Tips On Getting Your Loan

The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.

So, you want to get a loan? Here are some simple tips that might help you make more informed decisions about the type of loan you buy, and from whom.
As you would probably be aware, a loan varies according to:
  • The amount borrowed;
  • The interest rate;
  • The type of rate (fixed or variable);
  • The term (length in years) of the loan;
  • Deposit (downpayment);
  • Associated fees (broker, origination, prepayment etc.);
  • Insurance required by the lender.
When you get a loan, you are buying money for more than it cost the lender. Simple.
If you are comparing loan offers, it is a mistake to consider the interest rate alone. Depending on the type of loan, there may also be arrangement fees and *prepayment penalty* clauses to consider. Therefore, you should be sure to take into account the total cost of your loan when comparing options - and definitely before committing.
Keep a copy of every cheque you write for your loan. If you call your lender about your loan, make sure you get the full name of the person with whom you speak. Make a note of it. You may be dealing with a large bureaucracy, and will need to refer to this conversation later.
Do a budget. Make sure you use realistic figures. Keep all of your receipts, or keep a record, for all of the money that you spend for a month. Use that to help you compile the first draft.
Be prepared to review and update it regularly. A co-ordinated budget allows you to get the most loan for your money without beggaring yourself, while getting rid of wasteful spending.
Where possible you should avoid loans that contain combinations of the following attributes:
  • Short-term;
  • High up-front fees;
  • High rates;
  • Balloon payments;
  • Excessively high late fees;
  • Prepayment penalties.
These loans can potentially swallow up any equity you may have, and ruin your financial position.
Beware of prepayment penalties. Many 'no fee' credit lines have a pre-payment penalty. There is no need to agree get a loan which contains any significant prepayment penalty, if you have good credit. One of the smartest things someone can do with a loan is to prepay it.
All you need to do is contact your lender and ask for its prepayment procedure. Then, every so often, check the loan balance the lender sends you, to make sure the additional payments have been accounted properly.
Be wary of promises of getting a loan quickly. Many borrowers are told that their loans will close within a particular time. They don't make payments on existing debts, in anticipation of the new loan.
After several delays, they can become delinquent, with no money from the new loan. Some mortgage companies then order new credit reports, and charge the borrowers higher fees, and a higher rate, because of the delinquent loans, which resulted from delays caused by the loan company!
Submit a neat application form; it shows you're business-like and efficient. It will be read and assessed by a human being; appearances count.
Only pay up-front fees to well-known or highly recommended institutions. While most institutions are reputable, it is always best to be cautious.
Don't sign documents without reading them. As soon as possible, before you close the deal, review the documents you'll be signing, and make sure you understand them, so you won't have to sign them in a hurry.
Keep your credit line as small as possible. You could be turned down for other loans, even when your credit line has a zero balance, since a large credit-line indicates a large potential outgoings.
If your spending is out of control, don't get a home equity credit line to pay off your credit cards. Don't put your home at risk by spending large amounts on your credit cards, after paying them off with your credit line.
Pay off small debts before the due date. Cancel credit cards you are not using. Loan officers tend to count the total line of credit - even if you owe nothing - as a liability. They will only cloud the picture. Close credit lines that you have no intention of using in the near future. Also look closely at the interest rates and fees, when deciding which cards to keep.
Choose a lender with a clean record with the industry watchdogs in your country. The mortgage industry receives a great number of complaints against it. In Australia, mortgage and finance brokers of any kind must be licensed with A.S.I.C, and all licensing information for brokers can be found on the A.S.I.C. website.
Shop for rates when the market is calm. Rates change from day to day, so compare lenders. The quotes you get should all be from the same time period.
Check your payments are correct - Do the mathematics. There's a one in ten chance you could be paying more than you should.
If you find yourself in a dispute with a lender about a payment or another issue, don't send correspondence to the same address you send your payment. You need to deal with the decision-makers, not the account clerks.

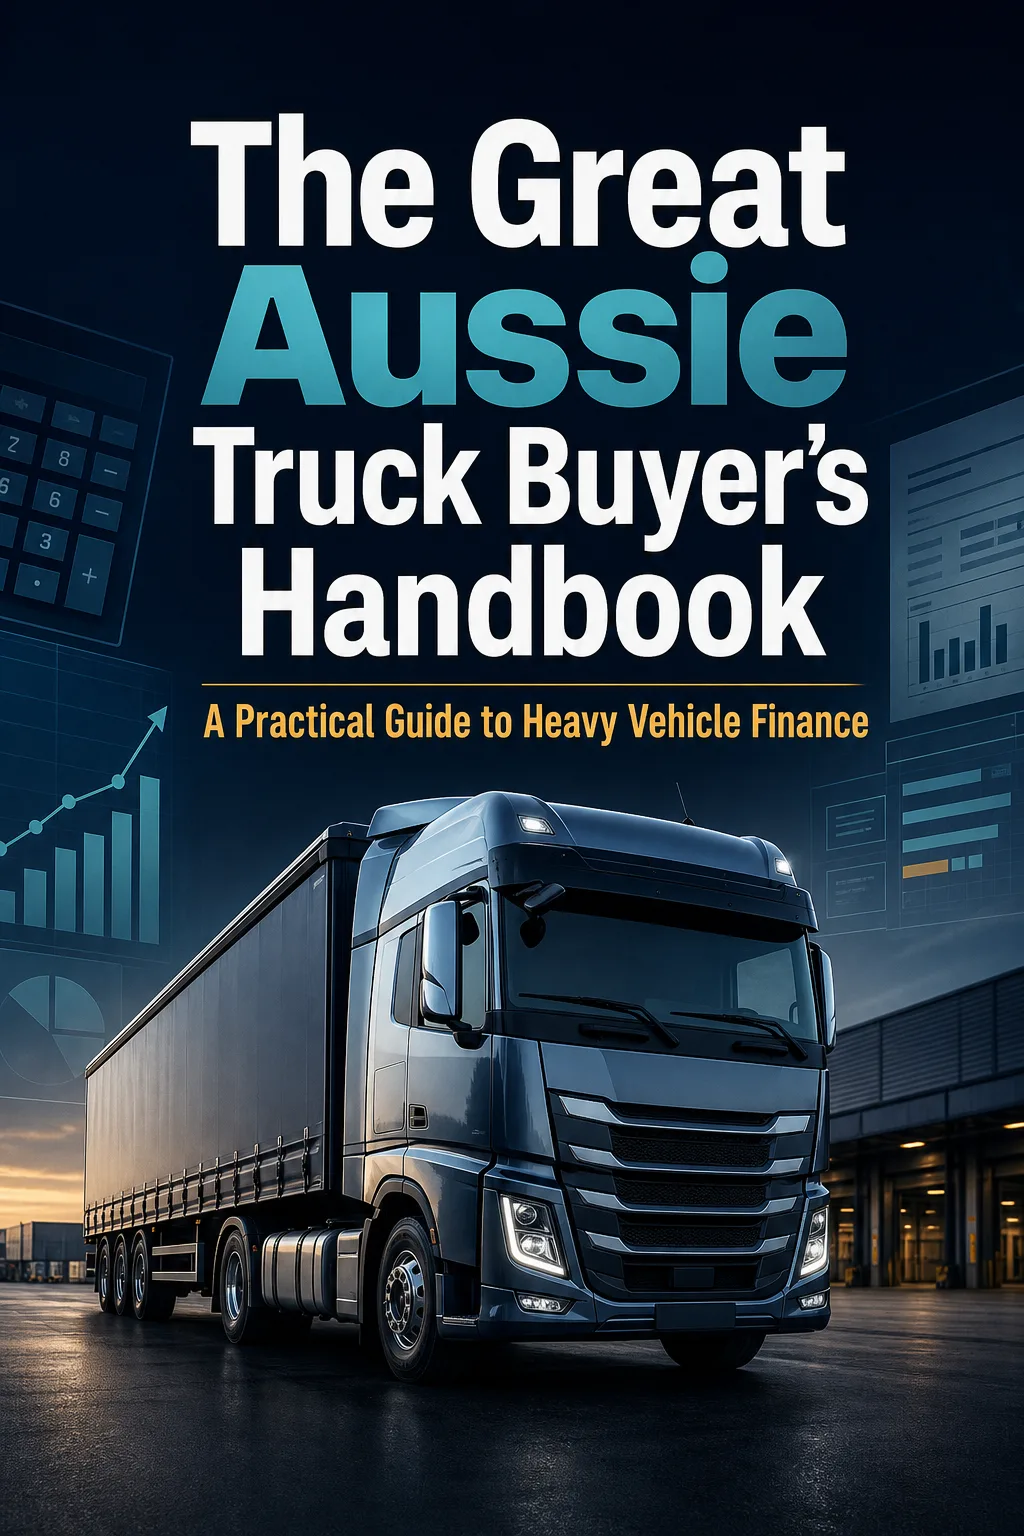
The Great Aussie Truck Buyer's Handbook: A Practical Guide to Heavy Vehicle Finance

The Great Aussie Truck Buyer's Handbook: A Practical Guide to Heavy Vehicle Finance image

Buying or financing a truck in Australia can affect more than the monthly repayment. The loan structure, fees, deposit, balloon payment, vehicle age and intended use can all shape cash flow and total borrowing cost. This practical guide is written for sole traders, tradies, logistics operators, fleet managers, small business owners and personal truck buyers comparing truck finance options. It explains commercial and personal truck loans, leases, chattel mortgages and hire purchase arrangements in clear, general terms. Inside, readers will find repayment factors, eligibility considerations, cost checklists, planning examples, case studies and questions to ask before making an informed finance enquiry.

Published: Sunday, 1st Aug 2021
Author: Paige Estritori

Rate this article

0 Comments

No comments yet. Be the first to share your thoughts.


Truck Loan Articles

Essential Document Checklist for Truck Loan Approval: What You Need to Know
Getting the right truck loan can be essential for business owners who rely on commercial vehicles. These loans cover a variety of commercial vehicle types and are crucial for ensuring your business operations run smoothly. Truck loans, specifically, provide the necessary finances to purchase trucks, which are indispensable in industries like logistics and delivery services across Australia. - read more
How to find the best insurance for your trucking business in Australia
As a trucking business owner in Australia, finding the right insurance is crucial to the protection of your business. To achieve this, it is important to first understand your specific business needs. Here are some factors to consider: - read more
The Pros and Cons of Leasing vs. Buying a Truck for Your Business
Small businesses that require regular transportation of goods may find it essential to purchase a truck. However, this acquisition can become a significant investment that requires careful consideration before making a decision. The two options available are buying or leasing a truck. In this article, we will explore the pros and cons of each option to help you make an informed choice. - read more
Maximizing Your Fleet Potential: How Truck Financing Shapes Success
Trucks play a pivotal role in the Australian logistics and transport industry, serving as the lifeblood that keeps commerce flowing. The dependable rumble of engines crisscrossing the nation's highways is more than just a symbol of industry; it's a critical component of productivity and economic stability. Without these workhorses facilitating the timely movement of goods, the Australian market would face significant challenges meeting the demands of both businesses and consumers alike. - read more
Essential Financial Safety Nets for Aussie Truck Drivers
Welcome to the road less traveled, where the rubber meets financial prudence. Truck driving in Australia is not just about long miles but also about ensuring financial stability amidst life's crossroads. As a truck driver, taking the wheel of your financial future is crucial, and that's what we'll navigate in this article. - read more

Finance News

Melbourne Boat Show Crowds Put Boat Budgets Back on the Table
10 Nov 2026: Paige Estritori
The 64th Melbourne Boat Show has given Australia’s boating market another useful demand signal, with organisers reporting more than 42,000 visitors at Docklands from 15 to 18 October 2026. The result was stronger than last year’s reported 39,000 attendance and came after four days of favourable weather, free entry and a waterfront layout spanning more than a kilometre of marina and land-based displays. - read more
New FLEETLEAP Alliance Targets Diesel Costs and EV Uncertainty
10 Nov 2026: Paige Estritori
A new Australian freight alliance, FLEETLEAP, has been launched to help truck operators make more informed decisions about fuel efficiency, emissions reduction and electric truck investment. Announced at the NatRoad National Conference on the Gold Coast on 6 November 2026, the project brings together transport associations, energy specialists, insurers and technology providers at a time when operating costs and technology choices are putting extra pressure on fleet planning. - read more
Higher cash rate raises the bar for business borrowing
10 Nov 2026: Paige Estritori
The Reserve Bank of Australia’s 3 November 2026 decision to lift the cash rate target by 25 basis points to 4.85 per cent has put borrowing costs back at the centre of small business planning. For Australian SMEs, the practical issue is not only whether rates rise on an existing facility, but whether budgets, pricing, stock decisions and expansion plans still work under a higher interest-rate path. - read more
Variable Rate Hikes Are Now Landing in Mortgage Budgets
10 Nov 2026: Paige Estritori
Australian mortgage holders are moving from rate speculation to repayment reality after the Reserve Bank of Australia lifted the cash rate target by 25 basis points to 4.85 per cent on 3 November 2026, with major and smaller lenders now passing through increases to variable home loan customers. - read more
Rate Rise Gives Boat Buyers a Fresh Reason to Recheck Finance Plans
05 Nov 2026: Paige Estritori
The Reserve Bank of Australia’s 3 November decision to lift the cash rate target by 25 basis points to 4.85 per cent, effective from 4 November 2026, gives prospective boat buyers a timely reason to revisit their finance assumptions before summer purchase activity intensifies. - read more

Knowledgebase
Personal Loan:
A Personal Loan is a means of obtaining finance from a financial institution or financial product provider and the lending criteria usually depends on criteria such as personal income and expenses, assets and liabilities, employment status and previo