The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.
Commercial vehicle finance can help Australian businesses acquire trucks, vans and other work vehicles without paying the full purchase price upfront. This guide explains the main loan and lease options, what affects costs, what lenders may review, and how to compare finance terms before applying.
What is a commercial vehicle loan?
A commercial vehicle loan is a finance arrangement used to buy or fund a vehicle for business purposes. In Australia, this can include trucks, delivery vans and specialised commercial vehicles used in transport, trade, logistics or other business operations.
The right structure depends on how the vehicle will be used, how long the business expects to keep it, available cash flow, tax considerations and whether ownership at the end of the term is important. This guide is educational only and should not be treated as personal financial, tax or legal advice.
Common commercial vehicle finance options in Australia
Businesses can usually consider several broad finance pathways. Each has different implications for ownership, repayments, documentation and flexibility.
Bank loans
Bank loans are a common option for businesses seeking commercial vehicle finance. They may offer competitive interest rates and flexible terms, although lenders often require detailed documentation, evidence of business income and, in some cases, security or collateral.
Non-bank lenders
Non-bank lenders may provide alternative commercial vehicle loan products and can sometimes offer more flexible application processes. They may be considered by businesses seeking faster access to finance or by applicants whose credit profile or documentation does not fit a traditional bank process. Terms, rates and fees still need careful comparison.
Dealer finance
Dealer finance can be convenient because the vehicle purchase and finance discussion may occur in one place. However, convenience should be weighed against the full cost of the loan, including the interest rate, establishment charges, account fees and any restrictions in the contract.
Finance leases
A finance lease can allow a business to use a vehicle without owning it outright during the lease term. This may suit businesses that want to preserve cash flow or upgrade vehicles more regularly. However, the business should understand end-of-term obligations, residual values and whether ownership is available or intended.
If you are weighing up a lease structure, a truck lease finance repayment estimate can help illustrate how repayments may change when lease terms or residual amounts differ.
Hire purchase agreements
Under a hire purchase arrangement, the business makes fixed payments over time and may own the vehicle after the final payment and any required conditions are met. This can appeal to businesses that want eventual ownership while spreading the cost over a set term.
Novated leases
Novated leases are generally associated with salary-packaged vehicles. They may be relevant in some employment arrangements, but they are not the same as a standard business truck loan. Employers and employees should understand the structure, tax treatment and responsibilities before proceeding.
Types of vehicles that may be financed
Commercial vehicle finance can apply to different vehicle types, depending on lender criteria and the business purpose. Examples include:
- trucks used to transport goods or equipment;
- delivery vans used for courier, retail or trade work;
- utility vehicles used by trades and service businesses;
- specialised vehicles used in a particular industry or niche market; and
- multiple vehicles for businesses expanding or replacing a fleet.
Before applying, it is useful to identify whether the vehicle is essential to current operations, intended for expansion, or being purchased to replace an existing asset. That purpose can influence the preferred finance term, repayment structure and documentation required.
What affects the cost of a commercial vehicle loan?
The total cost of finance is influenced by more than the advertised interest rate. When comparing options, consider how the following items work together.
| Factor |
Why it matters |
| Interest rate |
The rate affects repayment size and total interest paid over the loan term. |
| Loan term |
A longer term may reduce regular repayments but can increase total interest over time. A shorter term may increase repayments but reduce the time the debt remains outstanding. |
| Fees and charges |
Establishment fees, monthly fees, service charges and early repayment costs can affect the true cost of the loan. |
| Deposit or upfront contribution |
A higher upfront contribution may reduce the amount borrowed, but it also uses cash that may be needed elsewhere in the business. |
| Repayment frequency |
Weekly, fortnightly or monthly repayments can affect cash flow planning. |
| Balloon or residual amount |
A final lump sum or residual value may reduce regular repayments but creates a larger amount to manage at the end of the term. |
| Security and collateral |
Some lenders may use the vehicle or other assets as security, which can affect the lender's risk assessment and contract terms. |
Businesses can use a truck loan repayment calculator to model possible repayments, but calculator results are estimates only and depend on the assumptions entered.
Questions to ask before applying
Before starting an application, businesses should assess the purpose of the vehicle and how repayments will fit within normal cash flow. Useful questions include:
- How many vehicles are required now, and will more be needed later?
- Will the vehicle be used for delivery, freight, trade work or another business activity?
- Is ownership at the end of the term important?
- How much can the business contribute upfront without straining working capital?
- What repayment frequency best matches incoming revenue?
- Is there capacity to manage a balloon or residual payment if one applies?
- Are there tax, GST or depreciation issues to discuss with an accountant?
Tax treatment can vary depending on the business, vehicle use and finance structure. For a broader overview, see this guide to tax, GST and depreciation considerations for business truck finance.
The Great Aussie Truck Buyers Handbook
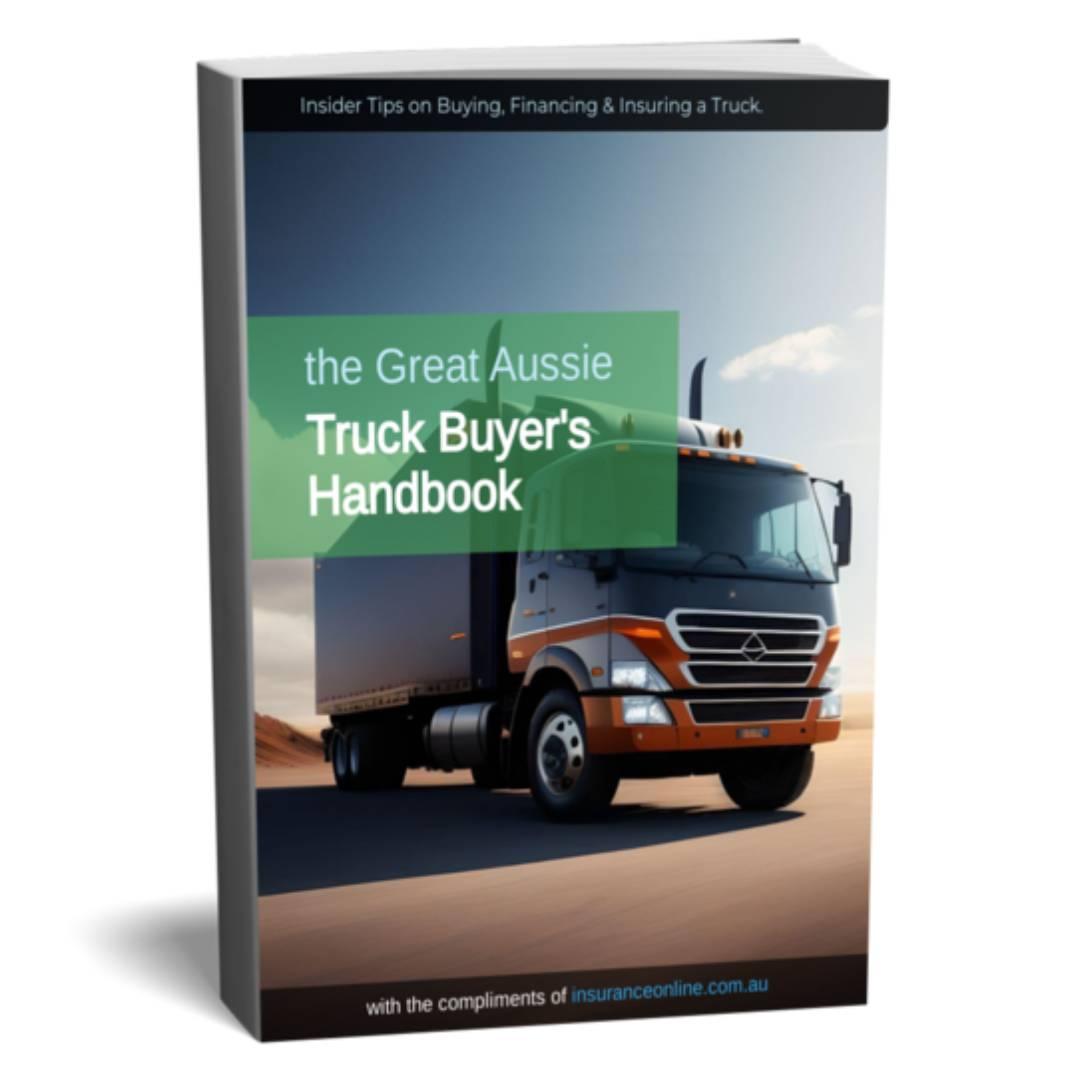
Discover the Insider Tips to Successfully Navigate the World of Truck Buying, Financing, and Insuring with "The Aussie Truck Buyer's Handbook: Insider Tips on Buying, Financing & Insuring a Truck." Whether you're a seasoned trucking professional or a new entrant in the industry, this comprehensive guide provides valuable insights, expert advice, and practical strategies to help you make informed decisions and optimize your trucking operations. From understanding your trucking needs to managing operating costs and complying with legal requirements, this eBook is your go-to resource for achieving success in the Australian trucking industry. Download your free copy today and take your trucking business to new heights!
How to compare lenders and finance offers
Commercial vehicle finance may be available through banks, non-bank lenders, dealer finance providers and brokers. The most suitable option is not determined by rate alone. A proper comparison should look at the full contract, including:
- the interest rate and whether it is fixed or variable;
- loan term and repayment schedule;
- upfront, ongoing and exit fees;
- security requirements;
- documentation and eligibility criteria;
- flexibility for additional or early repayments;
- balloon, residual or end-of-term obligations; and
- customer support and account management tools.
When you are ready to compare truck finance options, it is sensible to review more than one lender or product and check that the repayments and conditions align with the business plan.
Documents commonly requested for a commercial vehicle loan
Lenders may ask for documents that help them assess identity, business activity, income, creditworthiness and the vehicle being purchased. Requirements vary, but commonly requested information can include:
- personal identification for relevant applicants or directors;
- ABN or business registration details;
- business financial statements or income evidence;
- bank statements;
- details of existing debts or finance commitments;
- information about the vehicle, such as make, model, age and purchase price; and
- dealer invoice, contract of sale or other purchase documentation.
New businesses, sole traders and self-employed operators may be asked for different forms of evidence depending on lender policy. This overview of truck loan eligibility for new businesses and self-employed operators explains common assessment issues in more detail.
Application process: typical steps
While each lender has its own process, a commercial vehicle loan application will often involve the following steps:
- Define the vehicle requirement. Confirm the type of vehicle, expected use, estimated purchase price and whether the business wants ownership or use of the vehicle only.
- Review cash flow. Consider what repayment amount and frequency may be manageable alongside other business expenses.
- Gather documents. Prepare identification, business records, income evidence and vehicle details before submitting an application.
- Compare finance structures. Review loans, leases, hire purchase and dealer finance options where relevant.
- Submit accurate information. Incomplete or inconsistent details can delay assessment.
- Read the contract carefully. Check fees, repayment obligations, early repayment rules and end-of-term conditions before accepting.
Maintaining orderly business records and managing existing debts can help present a clearer financial picture to a lender, although no step guarantees approval or a particular rate.
Common mistakes to avoid
Focusing only on the interest rate
A low headline rate does not automatically mean the lowest overall cost. Fees, loan term, repayment flexibility and balloon payments can materially affect the total amount paid.
Overlooking hidden or ongoing fees
Ask about establishment fees, monthly account fees, service charges, early repayment costs and any other charges that may apply during or at the end of the finance term.
Not reading the fine print
Commercial loan contracts can contain important conditions about security, defaults, insurance, early payout, vehicle use and end-of-term obligations. If a term is unclear, seek appropriate professional guidance before signing.
Choosing terms that do not match business cash flow
A repayment schedule should fit the way the business earns income. For example, a business with seasonal revenue may need to think carefully about repayment timing and cash reserves.
Ignoring tax and accounting considerations
Vehicle finance can interact with tax deductions, depreciation and GST treatment. These areas can be complex and should be checked with a qualified tax adviser or accountant.
Key takeaways
Commercial vehicle loans and leases can support the purchase or use of trucks, vans and other business vehicles in Australia. The main options include bank loans, non-bank lender products, dealer finance, finance leases, hire purchase arrangements and, in some cases, novated leases.
Before applying, compare the full cost of finance, not just the interest rate. Review fees, repayment terms, security requirements, documentation, tax considerations and how the vehicle supports the business plan. A careful comparison can help a business choose a structure that is easier to understand and manage over the life of the finance arrangement.
Published: Thursday, 6th Mar 2025
Author: Paige Estritori





No comments yet. Be the first to share your thoughts.