Water upgrades move higher on the machinery finance agenda
Dry conditions are turning pumps, pipes and storage into strategic capital decisions
0
The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.
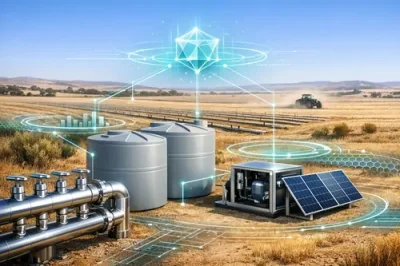
Recent rural reporting on dry seasonal conditions is again highlighting a practical reality for Australian farms: water infrastructure is not just a production issue, it is increasingly a finance decision.
As rainfall variability affects pasture growth, crop planning and livestock carrying capacity, many producers are reviewing whether existing pumps, tanks, troughs, bores and pipework can keep up with the next stretch of difficult conditions.
For farm businesses, this type of investment can be harder to assess than a single tractor or header purchase. Water upgrades often involve multiple assets, site works, electrical or solar components, freight, installation and commissioning. The final project cost can move quickly, especially where a farm is trying to improve water security across several paddocks or connect new storage into an older system.
That makes timing and structure important. A well-planned upgrade may reduce labour, lower water losses, improve grazing flexibility and protect productivity during dry periods. However, if the finance term, repayment frequency or balloon payment is poorly matched to farm income, the same investment can place avoidable pressure on working capital.
Producers considering irrigation systems or broader water infrastructure should look beyond the purchase price and ask several practical questions:
Will the upgrade generate measurable savings in labour, fuel, repairs or water use?
Does the equipment have a useful life that matches the proposed finance term?
Can repayments be aligned with livestock sales, grain income or other seasonal cash-flow points?
Are installation, freight, approvals and contingency costs included in the borrowing amount?
Could a staged upgrade reduce risk compared with financing the entire project at once?
The current focus on water security also reinforces the value of comparing new and used equipment carefully. Used pumps, tanks or irrigation components may reduce the upfront cost, but condition, compatibility and expected maintenance need to be factored into the equation. A cheaper item that requires frequent repairs may not improve cash flow once downtime and replacement parts are considered.
Before committing, farmers can estimate repayments under different deposit, term and residual assumptions. This helps show whether a proposed upgrade remains manageable if seasonal income is delayed or if operating costs rise.
The bigger lesson is that water resilience is becoming part of long-term machinery planning. For many enterprises, the next productivity gain may not come from more horsepower, but from the infrastructure that keeps paddocks, stock and crops operating when conditions tighten.
Please Note: We do not endorse any specific products or companies. Some content is sourced from third parties, including press releases, and may not be independently verified for accuracy or completeness.
Fresh housing finance reporting continues to show investor lending as one of the more resilient areas of the Australian mortgage market. For homeowners thinking about refinancing, that matters because lenders do not assess every borrower in the same way. Loan purpose, income stability, equity position and repayment buffer can all influence both approval prospects and the sharpness of the rate offered. - read more
Recent rural reporting on dry seasonal conditions is again highlighting a practical reality for Australian farms: water infrastructure is not just a production issue, it is increasingly a finance decision. As rainfall variability affects pasture growth, crop planning and livestock carrying capacity, many producers are reviewing whether existing pumps, tanks, troughs, bores and pipework can keep up with the next stretch of difficult conditions. - read more
The latest lending updates point to a familiar pattern: many Australians are still reviewing their loans, refinancing where they can, and looking for ways to bring borrowing costs under control. With household budgets stretched by groceries, rent, utilities, insurance and transport, even a modest reduction in repayments can feel meaningful. But for people carrying several debts at once, the decision to refinance or consolidate needs more care than simply chasing the lowest advertised rate. - read more
A fresh wave of interest in Australian asset-backed securities is worth watching for boat buyers, even if it sits several steps behind the showroom conversation. Recent financial market reporting points to continuing investor appetite for securitised lending products, where pools of loans are packaged and sold to institutional investors. For non-bank lenders, that demand can be an important source of funding and a signal that capital markets remain open. - read more
Fresh attention around Australian Taxation Office interest charges is giving small and medium-sized businesses another reason to treat tax debt as a front-line cash flow issue rather than a back-office problem. From the current income year, deductions are no longer available for general interest charge and shortfall interest charge amounts incurred on unpaid or underpaid tax liabilities. In practical terms, that can lift the after-tax cost of carrying ATO debt. - read more
Commercial vehicle finance can help Australian businesses acquire trucks, vans and other work vehicles without paying the full purchase price upfront. This guide explains the main loan and lease options, what affects costs, what lenders may review, and how to compare finance terms before applying. - read more
Truck loan repayments are shaped by the amount borrowed, interest rate, loan term, repayment frequency, fees, deposit and any balloon or residual amount. Understanding these inputs can help Australian business owners interpret repayment calculator results more clearly before comparing finance options. - read more
Small businesses that require regular transportation of goods may find it essential to purchase a truck. However, this acquisition can become a significant investment that requires careful consideration before making a decision. The two options available are buying or leasing a truck. In this article, we will explore the pros and cons of each option to help you make an informed choice. - read more
For many Australian businesses, purchasing a commercial vehicle is a significant investment that often requires financial assistance. Understanding the intricacies of truck financing is crucial, as the right loan can affect your company's bottom line and operational efficiency. With a plethora of lenders offering myriad loan products, choosing the most advantageous deal can be daunting. - read more
When purchasing a truck, whether for personal use or business, navigating the financial landscape can be daunting. This is where pre-approval comes into play. But what exactly does pre-approval mean in the context of buying a truck? - read more
Start Here
Get a free truck loan eligibility assessment and compare truck finance and leasing options
without accessing your credit file!!
Knowledgebase
Collateral: An asset that a borrower offers as a way for a lender to secure the loan.






No comments yet. Be the first to share your thoughts.